GeezerVison is showing github.com — Build software better, together
Here are
327 public repositories
matching this topic...
Language:
All
Filter by language
Sort:
Most stars
Sort options
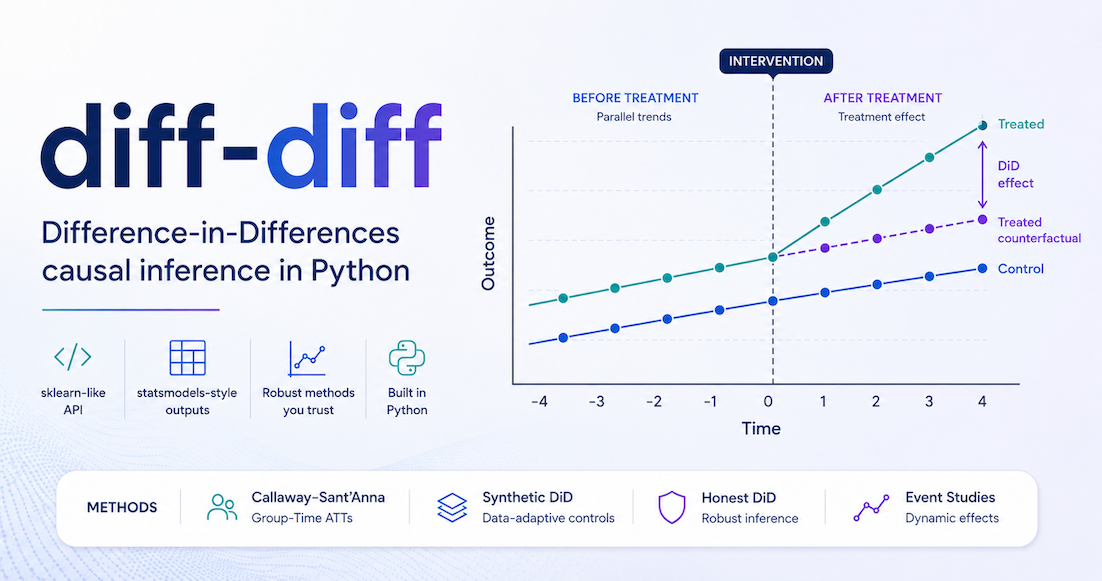
Difference-in-Differences causal inference in Python. Callaway-Sant'Anna, Synthetic DiD, Honest DiD, event studies. sklearn-like API, validated against R.
-
Updated
Nov 11, 2026
-
Python
Predicts how news-driven supply-chain shocks ripple across S&P 500 stocks, with an event-study backtest and a hash-chained public prediction ledger. Built on MIT open-source SEC supply-graph code.
-
Updated
Nov 12, 2026
-
JavaScript
Agent skills that help you publish in the AER faster — identification-first empirics, AEA-compliant replication, Keith-Head intros, R&R rebuttals for AER / AER:Insights / AEJ. | 助你更快发表 AER 论文的 agent skill 栈:识别优先实证、AEA 合规复现、Keith Head 式引言、R&R 审稿回复,覆盖选题到投稿全流程。
-
Updated
Jul 15, 2026
-
Python
Popular Econometrics content with code; Simple Linear Regression, Multiple Linear Regression, OLS, Event Study including Time Series Analysis, Fixed Effects and Random Effects Regressions for Panel Data, Heckman_2_Step for selection bias, Hausman Wu test for Endogeneity in Python, R, and STATA.
-
Updated
Apr 22, 2021
-
Stata
fast and flexible Difference-in-Differences
AI-powered trading research platform. Test any idea on stocks, futures, and crypto with event studies, backtesting, and statistical validation. MCP server with 8 tools. pip install varrd.
-
Updated
Aug 31, 2026
-
Python
Estimation of Difference-in-Differences Treatment Effects with Staggered Treatment Onset Using Heterogeneity-Robust Two-Way Fixed Effects Regressions
-
Updated
Sep 26, 2026
-
Stata
An Implementation of Parametric and Nonparametric Event Study

archived : use csdid instead
Research code and data for an event-study analysis of stock-market responses to U.S. Supreme Court decisions.
-
Updated
May 14, 2017
-
Jupyter Notebook

This repository introduces the event study model.
-
Updated
Sep 5, 2023
-
Stata
Replication and analysis of album releases, streaming volume and US traffic fatalities
-
Updated
Oct 31, 2026
-
Python
Open Agent Skill for exploratory financial astrology event studies across investment assets
-
Updated
Jun 5, 2026
-
Python
Polars event-study research for ES/NQ intraday futures: MSS, CISD, SMT, RSI/volume divergences, session/momentum/volume filters.
-
Updated
Oct 5, 2026
-
Python
GPU-accelerated R package for causal inference: Callaway-Sant'Anna, DIDmultiplegtDYN, fect, TestMechs, HonestDiD. 60x faster than reference on R backend; CUDA acceleration in development.
可解释的A股短线事件研究工具:涨跌停事件表、时间序列验证、样本外纪律与条件组合检查
-
Updated
Aug 22, 2026
-
Python
End-to-End Python framework reproducing Dolphin et al.'s (2026) grounded event extraction (from SEC 8-K filings) method. Extracts taxonomy-validated, quote-grounded event tags via LLMs, then proves economic significance through variance-standardized abnormal returns (SAR), Kruskal-Wallis tests, and bootstrap variance decomposition over CRSP data.
-
Updated
Jul 18, 2026
-
Jupyter Notebook
Live macro terminal: classifies the US economy into four regimes, scores recession odds, runs event studies and basket hedges. React, TypeScript and Vite on Vercel; FastAPI on Render; Python (pandas, scikit-learn, riskfolio-lib) over SQLite, refreshed by GitHub Actions from FRED, EODHD, Yahoo, Finnhub and NewsAPI. AI by Claude and Perplexity.
-
Updated
Nov 12, 2026
-
Python
R package: crseEventStudy

End-to-end incrementality sandbox on M5-style retail data (DiD + Synthetic Control + placebo tests) with Streamlit dashboard.
-
Updated
Dec 29, 2025
-
Python
Add this topic to your repo
To associate your repository with the
event-study
topic, visit your repo's landing page and select "manage topics."
Learn more
|